
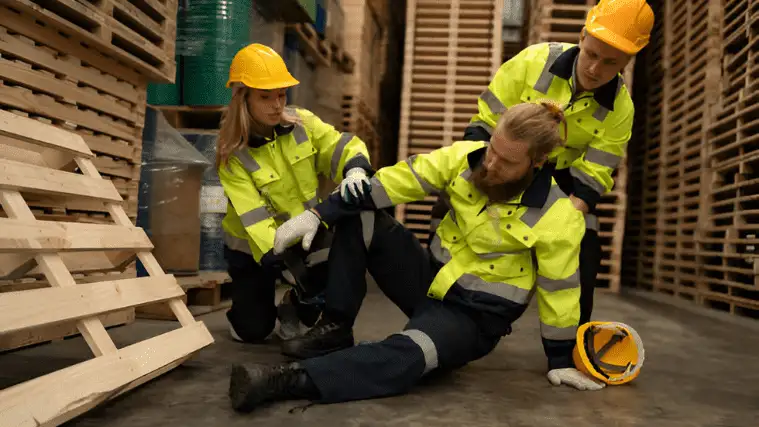
Workers' compensation insurance covers employees who suffer a work-related injury, illness, or repetitive stress condition. Workers' comp pays for medical treatment, ongoing care and rehabilitation, lost wages, disability benefits, vocational retraining, and death benefits. The same policy also protects the employer from most injury lawsuits and pays legal defense costs.
Work injuries happen far more often than most business owners expect. Private employers reported 2.5 million nonfatal workplace injuries and illnesses in 2024, according to the U.S. Bureau of Labor Statistics (BLS). Below, we break down every benefit workers' comp pays, what makes an injury qualify, what workers' comp leaves out, where the benefit limits sit, and what employers should do on the day someone gets hurt.
What Does Workers' Compensation Insurance Cover?
Workers' compensation insurance covers six core benefits for employees who get hurt or sick because of their job:
- Medical treatment: Emergency room visits, doctor visits, surgery, hospital stays, prescription medication, and medical equipment like crutches and braces.
- Ongoing care and rehabilitation: Physical therapy, occupational therapy, and chiropractic care a doctor prescribes for long-term recovery.
- Lost wages: A weekly check that replaces part of the employee's regular income while a doctor keeps them off work.
- Disability benefits: Short-term or long-term payments when the work injury causes a temporary or permanent disability.
- Vocational training: Job retraining and placement help when a permanent restriction blocks a return to the old job.
- Death benefits: Funeral and burial expenses, plus income support for surviving dependents if a worker dies from a job-related incident.
Workers' comp also gives the business owner two protections of its own. Employer's liability coverage pays if an employee sues over a work injury, and legal defense coverage pays attorney fees and court costs tied to those suits.
A workers' compensation insurance policy pays these benefits on a no-fault basis. No-fault means the injured employee receives care whether the accident came from their own mistake, a coworker's mistake, or nobody's mistake at all.
The no-fault system moves serious money every year. U.S. workers' comp programs paid $64.1 billion in benefits in 2023, and medical care made up more than 47% of that total, according to the National Academy of Social Insurance (NASI). Every one of those dollars starts with the same test, which is whether the injury is truly work-related.
What Injuries and Illnesses Qualify for Workers' Comp?
Injuries and illnesses qualify for workers' comp when they arise out of and in the course of employment. "Arising out of" means the job caused the harm. "In the course of" means the harm happened while the employee was doing their work, at a place they were expected to be.
Qualifying claims fall into three groups. Sudden injuries come from a single event, like a fall from a ladder, a cut from a saw, or a back strain while lifting a pallet. Occupational illnesses develop from the work environment, like lung disease from silica dust or skin damage from chemical exposure. Repetitive stress injuries build slowly over months or years, like carpal tunnel syndrome from constant typing or tendinitis from repeated overhead reaching.
Repetitive stress claims are bigger than most people think. Overexertion, repetitive motion, and bodily conditions caused about 946,000 serious cases with days away from work, job restriction, or transfer during 2023 and 2024, the top cause in the BLS data. Occupational illnesses are smaller in number but still real, with BLS counting 148,000 illness cases in private industry in 2024.
Coverage also travels with the employee. Workers' comp covers injuries that happen away from the main workplace when the employee is performing job duties, such as making deliveries, visiting a client, attending a work training, or working on a job site across town.
What Is the Most Common Workers' Comp Claim?
The most common workers' comp claim is a strain or sprain, which makes up 38% of claims in the Travelers Injury Impact Report, a study of more than 1.2 million claims. Fractures follow at 13%, then contusions at 8%, inflammation at 7%, and dislocations at 7%.
The causes behind those claims follow a clear pattern. Overexertion causes 29% of claims, slips, trips, and falls cause 23%, and being struck by an object causes 13%, according to the same Travelers report. Strains, sprains, and fractures all lead to the same first need after the injury, which is medical care.
What Medical Costs Does Workers' Comp Pay For?
Workers' comp pays for all reasonable and necessary medical care tied to the work injury. That medical care includes ambulance rides, emergency room treatment, doctor visits, surgery, hospital stays, X-rays and MRIs, prescription medication, and medical supplies like crutches, braces, and artificial limbs.
Medical care is the largest share of most serious claims. The average lost-time workers' comp claim cost $50,076 for accidents in 2023 and 2024, combining medical and wage costs, according to the National Safety Council (NSC) using data from the National Council on Compensation Insurance (NCCI).
Workers' comp medical benefits apply only to your own employees. A customer who slips on a wet floor in your shop is a third party, and that customer's injury falls under general liability instead.
Does Workers' Comp Cover 100% of Medical Bills?
Yes, workers' comp covers 100% of approved medical bills for a work injury, with no deductible, copay, or coinsurance for the employee. The insurance carrier pays the medical provider directly, so the injured worker never sees a bill for authorized treatment.
The word "approved" matters. In many states, the employer or insurer chooses the first treating doctor, and the employee can request a change through a set process. Treatment from an unauthorized provider, or care for a condition unrelated to the work injury, falls outside the 100% coverage.
Does Workers' Comp Cover Physical Therapy?
Yes, workers' comp covers physical therapy, along with occupational therapy, chiropractic care, and any other rehabilitation a doctor prescribes for the work injury. Physical therapy often runs for weeks after the first treatment, and workers' comp pays for every approved session.
Rehabilitation also bridges the gap back to work. BLS data shows the median case involving job transfer or restriction lasted 15 days in 2023 and 2024. Those recovery days away from full duty mean missed paychecks, and missed paychecks are where wage benefits begin.
How Does Workers' Comp Replace Lost Wages?
Workers' comp replaces lost wages by paying the injured employee a weekly check, usually two-thirds (66⅔%) of their average weekly wage, for as long as a doctor keeps them off work. Each state sets its own weekly maximum and minimum, so very high earners receive less than a full two-thirds.
Wage checks start after a short waiting period, usually 3 to 7 days depending on the state. When the time off stretches past a set number of days, most states pay back the waiting period too, so longer recoveries are paid from day one.
Wage benefits also keep more of their value than a paycheck. Workers' comp payments for a job-related injury or sickness are fully exempt from federal income tax, according to IRS Publication 525.
Can I Get Money From Workers' Comp?
Yes, you can get money from workers' comp when a work injury or illness keeps you off the job or forces you into a lower-paying light-duty role. The insurance carrier sends weekly wage replacement checks during recovery.
Workers' comp money can also come later in the claim. An employee left with lasting damage, like reduced motion in a shoulder, receives a permanent disability award based on the doctor's impairment rating once healing is complete.
How Much of Your Paycheck Does Workers' Comp Pay?
Workers' comp pays about two-thirds of your paycheck, calculated as 66⅔% of your average weekly wage before the injury. A warehouse worker averaging $900 a week, for example, receives $600 a week in wage benefits while off work.
The average weekly wage usually looks back over the year before the injury, so overtime and regular second-shift pay count toward the figure. Short absences stay in the temporary wage category, while longer or lasting injuries move into disability benefits.
What Disability Benefits Does Workers' Comp Provide?
Workers' comp provides four types of disability benefits: temporary total, temporary partial, permanent partial, and permanent total disability. Each disability type depends on two questions, which are whether the employee can work at all and whether the injury will fully heal.
The four disability classes line up like this:
Disability benefits grow with the severity of the injury. Dislocations cost almost three times the average claim among the most common injury types, according to the Travelers Injury Impact Report, largely because they keep workers in temporary disability longer. Some of those workers never return to the same job, and that outcome brings in vocational rehabilitation.
What Is Vocational Rehabilitation in Workers' Comp?
Vocational rehabilitation in workers' comp is job retraining, skills testing, and placement help for an employee who cannot return to their old job. A roofer with a permanent shoulder restriction, for example, might retrain for estimating or project scheduling instead of climbing ladders.
Vocational rehabilitation helps the business too. Retraining keeps an experienced employee on the team in a new role, so the company holds on to their knowledge instead of hiring and training a replacement. The most serious outcome of a work injury, though, ends any chance of returning to work.
What Death Benefits Does Workers' Comp Pay to Families?
Workers' comp pays two death benefits to families: funeral and burial expenses, and weekly income payments to the worker's dependents. Death benefits apply when a work accident or occupational disease causes the employee's death.
Fatal work injuries remain a real risk in many trades. The BLS Census of Fatal Occupational Injuries counted 5,070 fatal work injuries in the United States in 2024, with transportation, construction, and heavy industry carrying the highest exposure.
Dependent payments usually equal a share of the worker's average weekly wage, and the share grows with the number of dependents. State law caps both the weekly amount and the number of weeks paid. Because these death benefits stop at a set limit, many families pair them with personal life insurance for long-term income.
Every benefit so far goes to the employee or the employee's family. Workers' comp also gives the business owner a separate layer of protection.
How Does Workers' Comp Protect the Employer?
Workers' comp protects the employer through the exclusive remedy rule, employer's liability coverage, and legal defense costs. These three protections turn an unpredictable lawsuit risk into a predictable insurance claim.
The exclusive remedy rule is the trade at the heart of the system. An employee who accepts workers' comp benefits gives up the right to sue the employer for that injury in most cases. The employee gets guaranteed medical care and wage checks without proving fault, and the employer avoids jury awards for pain and suffering.
A standard workers' comp policy bundles both protections into two parts. Part One pays the state-required benefits to injured workers. Part Two, called employer's liability, pays when a lawsuit gets around the exclusive remedy rule, such as a spouse suing for loss of companionship or a third party suing the employer after a work accident.
Insurance carriers handle most of this protection. Private insurers paid 55.6% of all workers' comp benefits in 2023, according to NASI, with self-insured employers and state funds paying the rest.
Lawsuits from customers, vendors, and the public sit outside workers' comp entirely, which is why most businesses carry liability insurance alongside it. That outside edge is one of several limits on what workers' comp pays.
What Is Not Covered by Workers' Compensation Insurance?
Workers' compensation insurance does not cover injuries from commuting, intoxication, intentional acts, horseplay, or anything that happens off the clock or outside job duties. The common exclusions include:
- Commuting: Injuries during the normal drive to and from work, unless travel is an official part of the job.
- Intoxication: Injuries caused by the employee's use of alcohol or illegal drugs.
- Intentional acts: Self-inflicted injuries and injuries from a fight the employee started.
- Horseplay and willful misconduct: Injuries from goofing around, breaking a known safety rule, or refusing to use provided safety equipment.
- Off-the-clock activities: Injuries during personal time, like a weekend pickup game or an errand unrelated to work.
- Non-employees: Independent contractors, customers, and visitors in most cases.
- Employment practices claims: Lawsuits over discrimination, harassment, or wrongful termination.
Each exclusion leaves a risk that another policy has to carry. These coverage gaps are why workers' comp works best as one piece of a full business insurance plan.
Does Workers' Comp Cover Everything?
No, workers' comp does not cover everything. Workers' comp pays medical care, partial wages, disability, rehabilitation, and death benefits, and nothing beyond those set categories.
Workers' comp does not pay for pain and suffering, emotional distress damages, punitive damages, or 100% of lost wages. Workers' comp also does not pay for damaged property, like a broken company truck or a crushed piece of equipment, since property losses belong to commercial property and auto policies.
Does Workers' Comp Cover Injuries While Driving for Work?
Yes, workers' comp covers injuries while driving for work when the trip is part of the job, such as deliveries, driving between job sites, or visiting a client. The regular commute from home to the workplace and back stays excluded.
Work driving claims cost more than most. Motor vehicle accidents cause 5% of workers' comp claims and cost 33% more than the average claim, according to the Travelers Injury Impact Report.
A work vehicle crash usually triggers two policies at once. The employee's injuries go through workers' comp, while damage to the vehicle and injuries to other drivers fall under commercial auto insurance. Even fully covered claims like these, though, run into benefit limits.
Is There a Limit for Workers' Compensation?
Yes, there is a limit for workers' compensation on wage and disability benefits, though medical care for an approved claim usually has no dollar cap. Each state sets a maximum weekly benefit, a minimum weekly benefit, and a limit on how many weeks each benefit type lasts.
State limits change every year with average wages. In Alabama, the maximum weekly benefit rose to $1,219 for injuries on or after July 1, 2026, and the minimum rose to $335, under the state's annual rate adjustment.
Duration limits follow the same state rules. The state's Department of Workforce lists 300 weeks for temporary partial and permanent partial disability, 500 weeks for death benefits, and no time limit for temporary total or permanent total disability. Burial expenses top out at $6,500, and a worker who dies with no dependents leaves a $7,500 lump sum to their estate.
What Body Part Pays the Most Workers' Comp?
The head and central nervous system pays the most workers' comp, averaging $97,603 per lost-time claim for accidents in 2023 and 2024, according to NSC data drawn from NCCI. Head and spine injuries cost the most because they need long hospital stays, specialist care, and long stretches away from work.
The costliest body parts compare against the average claim like this:
Part of BodyAverage Cost per Lost-Time Claim (2023 to 2024)Head or central nervous system$97,603Multiple body parts$82,346Neck$75,304Hip, thigh, and pelvis$69,443Leg$67,542Arm or shoulder$57,621All claims combined$50,076
The type of injury and its cause push costs even higher. Amputations average $149,543 per claim, and motor-vehicle crashes are the costliest cause at $93,105 per claim, according to the same NSC data. Fleet safety rules for business vehicles are one of the most direct ways to bring those numbers down. Cost only matters, however, for the people a policy actually covers.
Who Is Covered by Workers' Compensation?
Workers' compensation covers employees, including full-time, part-time, and seasonal workers, from their first day on the job. Coverage follows the employment relationship, not the job title or the number of hours worked.
Workers' comp reaches a huge share of the workforce. U.S. workers' comp programs covered nearly 150 million jobs in 2023, according to NASI.
Some workers fall outside the requirement. Independent contractors, sole proprietors, business partners, domestic workers, farm laborers, and casual workers are often exempt, depending on the state. Alabama generally requires coverage for employers with five or more employees, while other states start at one employee.
Owners who are not required to carry coverage often buy workers' comp coverage anyway, because a single lost-time claim averages $50,076. Misclassifying an employee as a contractor creates the same exposure, since the state can treat that worker as an employee after an injury. Once the right people are covered, the last piece is knowing what to do on the day someone gets hurt.
What Should Employers Do After a Workplace Injury?
Employers should get the injured worker medical care first, then report and document the injury quickly. Fast action keeps the claim clean and gets benefits flowing sooner. The steps run in this order:
- Get medical care right away. Call 911 for emergencies, and send the employee to the approved provider for everything else.
- Collect the employee's notice of injury. Most states set short deadlines for reporting, often within days of the accident.
- Document the scene. Record the date, time, location, task being performed, witnesses, and photos.
- File the First Report of Injury with your insurance carrier. The carrier opens the claim and starts medical and wage payments.
- Stay in contact during recovery. Regular check-ins keep the employee informed and connected to the team.
- Build a return-to-work plan. Light-duty tasks bring the employee back sooner and lower the wage cost of the claim.
Return-to-work planning pays off because recovery time is the hidden cost of every claim. Employees injured on the job miss an average of 71 workdays, according to the Travelers Injury Impact Report.
Claims also run smoother with an agent on your side. We walk clients through the claims process with their carrier, and at renewal we compare quotes from multiple carriers so coverage keeps pace with payroll and job changes.
Frequently Asked Questions
Does Workers' Comp Cover Pre-Existing Conditions?
Workers' comp covers pre-existing conditions when job duties aggravate, speed up, or worsen them. An old knee injury that flares up from daily ladder climbing, for example, can qualify. The claim turns on medical evidence showing the work made the condition worse.
Does Workers' Comp Cover Mental Stress?
Workers' comp covers mental stress in limited cases, usually when the stress ties to a physical work injury or a sudden, unusual work event. Many states exclude purely emotional claims with no physical trauma. Ordinary job pressure, like deadlines or performance reviews, does not qualify.
Does Workers' Comp Pay for Pain and Suffering?
No, workers' comp does not pay for pain and suffering. The no-fault system trades pain and suffering damages for guaranteed medical care and wage checks, and the exclusive remedy rule blocks most lawsuits that would seek those damages from the employer.
Does Workers' Comp Cover Independent Contractors?
No, workers' comp does not cover true independent contractors in most cases. Contractors carry their own coverage or none at all. A worker labeled a contractor but treated like an employee, with set hours and company tools, may still receive benefits after an injury.
Does Workers' Comp Cover Remote Workers?
Yes, workers' comp covers remote workers injured while doing job tasks at home. A fall while carrying work files to a home office qualifies, while a kitchen burn during a personal lunch break does not. The same course-of-employment test applies at home as in the office.
Is Workers' Comp Required for Small Businesses?
Yes, workers' comp is required for most small businesses with employees, though each state sets its own employee threshold. Some states require coverage from the first employee, and Texas is the main state where coverage stays optional. Business owners can start coverage through a quick application with basic payroll and job details.
The Bottom Line
Workers' compensation insurance covers the full cost of a work injury on the employee's side: medical treatment, rehabilitation, lost wages, disability, retraining, and death benefits. On the employer's side, workers' comp blocks most injury lawsuits and pays legal defense costs. Commuting, intoxication, horseplay, off-the-clock activities, and non-employees fall outside coverage, and state limits cap wage and death benefits.
The right policy depends on your payroll, your industry, and the work your team does every day. We help business owners across North Alabama find workers' comp coverage that fits their crew. When you are ready to talk it through, the team at UR Choice Insurance is here, and you can reach our team any time.